Address:
1601 Adeola Hopewell, Victoria Island.
13 David Bodunrin Caulcrick Close, Ikeja
Suit no 1058, 1060, KingfemGa 247 Plaza, 264 Ahmadu Bello Way, Mabushi Abuja.
Phone No.:
+234 (1) 234-5678
Address:
1601 Adeola Hopewell, Victoria Island.
13 David Bodunrin Caulcrick Close, Ikeja
Suit no 1058, 1060, KingfemGa 247 Plaza, 264 Ahmadu Bello Way, Mabushi Abuja.
Phone No.:
+234 (1) 234-5678
Follow this source
Get more financial contents from us
Nigeria’s financial market is entering a new phase as the Central Bank of Nigeria (CBN) adjusts its monetary policy framework in response to changing economic conditions. For investors, business owners, and individuals looking to build long-term wealth, understanding this development is essential to making informed financial decisions.
At its 307th Monetary Policy Committee (MPC) meeting, held on September 21 and 22, 2026, the CBN reset the Monetary Policy Rate (MPR) from 26.5% to 23%. Although the 3.5-percentage-point reduction may appear to signal a major shift towards cheaper borrowing, the CBN clarified that the decision was primarily an operational realignment intended to improve how monetary policy influences financial markets.
So, what does this decision mean for Nigeria’s economy? How could it affect savings, fixed-income investments, equities, businesses, and other investment opportunities? Most importantly, how can investors position their portfolios to respond to the changing financial landscape?
This article explores the key takeaways from the latest MPC meeting and the practical considerations investors should keep in mind.
The Monetary Policy Committee is the body within the Central Bank of Nigeria responsible for making key monetary policy decisions aimed at maintaining price stability and supporting a stable financial system.
During its meetings, the MPC reviews indicators such as inflation, economic growth, foreign exchange conditions, liquidity, and global economic developments. Based on its assessment, it decides whether to adjust or maintain the Monetary Policy Rate and other policy instruments.
The MPR serves as a key benchmark for monetary policy. Changes to it can influence money market conditions, lending rates, fixed-income yields, and the broader investment environment, although these effects do not always occur immediately or in equal measure.
For investors, MPC decisions provide important information about the direction of monetary policy and the factors that could influence investment performance.
At its September meeting, the MPC announced three major decisions:
Monetary Policy Rate: Reset from 26.5% to 23%.
Standing Facilities Corridor: Recalibrated to +50 and -300 basis points around the MPR.
Cash Reserve Requirement: Maintained at 45% for deposit money banks, 16% for merchant banks, and 75% for non-Treasury Single Account public-sector deposits.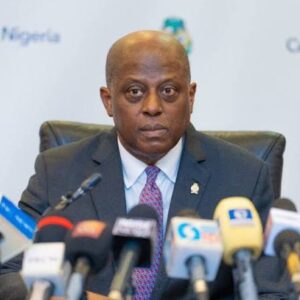
The most prominent development was the adjustment of the MPR by 350 basis points.
However, the CBN explained that this was not a conventional move towards monetary easing. The previous policy rate had become disconnected from prevailing money market rates, weakening its effectiveness as the main signal of monetary policy.
The adjustment was therefore intended to bring the benchmark closer to market realities and strengthen the transmission of monetary policy across the financial system.
The distinction matters: investors should not automatically assume that the decision will lead to immediate reductions in bank lending rates or a guaranteed rise in asset prices.
Source: Central Bank of Nigeria, Monetary Policy Decisions, September 21–22, 2026.
Several economic developments informed the decision.
1. Improving Foreign Exchange Conditions
The CBN highlighted improvements in Nigeria’s external position and foreign exchange conditions. Stronger external reserves and increased foreign exchange inflows can help improve market confidence and reduce some of the pressures associated with currency instability.
For investors, exchange rate stability matters because it influences import costs, business expenses, inflation expectations, and the naira value of foreign-currency investments.
However, improved conditions do not eliminate currency risk. Exchange rates remain sensitive to global developments, domestic policy, trade flows, and investor sentiment.
2. Changes in Inflation and Economic Activity
The CBN also pointed to improving macroeconomic conditions and the effects of previous monetary tightening.
When inflation moderates, the pressure on the central bank to maintain exceptionally restrictive monetary conditions may change. Nevertheless, lower inflation does not mean that prices have returned to previous levels. It generally means that prices are rising more slowly.
This distinction is important for investors. The objective is not simply to earn a nominal return but to preserve and potentially grow purchasing power after accounting for inflation.
3. Strengthening Monetary Policy Transmission
The decision also addressed the gap between the official MPR and rates prevailing in the money market.
By recalibrating the policy framework, the CBN aims to make its benchmark more effective in influencing financial conditions.
For investors, this means paying attention not only to the announced MPR but also to actual Treasury bill yields, bond yields, deposit rates, lending costs, and market liquidity.
The implications will vary depending on an investor’s objectives, investment horizon, and tolerance for risk.
1. Fixed-Income Investors Should Review Their Portfolios
Fixed-income investments, including Treasury bills and government bonds, are particularly sensitive to interest rate expectations.
When market interest rates decline, the prices of existing fixed-rate bonds can rise, all else being equal. This is because their existing coupon payments may become more attractive relative to newly issued securities.
For example, an investor holding an existing bond with a fixed coupon could benefit from a price increase if comparable market yields subsequently decline. However, the outcome depends on the bond’s maturity, coupon, current market price, credit risk, and prevailing yields.
The reverse is also possible: if market yields rise, existing fixed-rate bond prices may fall.
2. Investors Should Pay Attention to Money Market Opportunities
Money market instruments can be useful for investors seeking relatively short-term placements, liquidity, and a defined investment horizon.
Treasury bills and other short-term instruments may become more attractive or less attractive as market yields adjust to changing monetary conditions.
However, the MPR is not the same as the yield on a Treasury bill or the interest rate offered on a bank deposit. Actual returns depend on market demand, auction outcomes, instrument maturity, fees, and the terms offered by the provider.
3. Equity Investors Should Look Beyond the Headline Rate
Changes in monetary policy can influence the stock market through borrowing costs, investor sentiment, company earnings, and the relative attractiveness of fixed-income assets.
If market borrowing costs eventually decline, some businesses may benefit from lower financing expenses. Companies that rely heavily on credit to fund operations or expansion could experience improved financial flexibility.
Lower yields on competing fixed-income instruments may also encourage some investors to reassess their allocation to equities.
Nevertheless, these outcomes are not automatic. A lower policy rate does not guarantee a stock market rally, and a company’s performance still depends on its earnings, debt, cash flow, management, competitive position, and valuation.
What investors can do:
Focus on companies with sustainable business models, sound financial positions, credible growth prospects, and valuations that justify their risks. Evaluate company fundamentals instead of buying shares solely because the CBN has adjusted its policy rate.
Diversification across suitable assets and sectors can also help reduce exposure to risks associated with individual companies.
4. Businesses and Entrepreneurs Should Review Financing Decisions
Monetary policy influences the broader cost and availability of credit, although the effect on commercial lending rates can be delayed or limited.
The September adjustment should not be interpreted as a guarantee that business loans will immediately become cheaper. Banks consider their own funding costs, credit risk, operating expenses, collateral requirements, and other factors when setting lending terms.
5. Investors With Foreign-Currency Exposure Should Monitor Exchange Rate Risk
Improvements in foreign exchange conditions may support greater confidence in Nigeria’s financial markets. However, exchange rate movements remain uncertain.
Investors holding dollar-denominated assets, receiving foreign income, or planning international payments should consider how movements in the naira could affect their financial position.
For example, a foreign-currency investment may gain or lose value when converted into naira, even if the underlying asset’s price remains unchanged in its original currency.
6. Long-Term Investors Should Maintain a Clear Investment Strategy
Monetary policy decisions can create opportunities, but frequent portfolio changes based on individual announcements may expose investors to unnecessary costs and poorly timed decisions.
Long-term investors should assess how their portfolio aligns with their financial goals, time horizon, liquidity requirements, and ability to withstand losses.
The most practical response to the MPC decision is to turn the policy announcement into a structured investment review.
Here are five steps investors can consider:
Step 1: Review your current investments.
Identify how much is allocated to cash, money market instruments, fixed-income securities, equities, property, and other assets. Understand the risks and expected returns of each holding.
Step 2: Compare current market yields.
Look beyond the 23% MPR and examine actual yields on available instruments. Compare maturity, liquidity, fees, taxation where applicable, and the risks involved.
Step 3: Match investments to your time horizon.
Funds needed in the near term may require greater liquidity and lower exposure to price volatility. Long-term funds may allow a broader investment mix, depending on your financial circumstances and risk tolerance.
Step 4: Assess the real return.
A positive nominal return does not necessarily mean your wealth is growing in purchasing-power terms. Compare the expected investment return with inflation and relevant costs.
Step 5: Monitor economic developments.
Pay attention to inflation data, subsequent MPC decisions, Treasury bill auctions, bond yields, foreign exchange conditions, and company earnings. These indicators provide additional context for investment decisions.
The CBN has indicated that its future decisions will remain data-dependent. Investors should therefore avoid assuming that further rate reductions are inevitable.
While the changing monetary policy environment may create opportunities, several risks remain.
Inflation risk: If inflation remains elevated or accelerates again, the real value of investment returns may be reduced.
Interest rate risk: Bond prices can fall when market yields rise, particularly for longer-duration fixed-rate securities.
Liquidity risk: Some investments may be difficult to sell quickly without accepting a discount.
Credit risk: An issuer or borrower may fail to meet its payment obligations.
Currency risk: Exchange rate movements can affect the naira value of foreign-currency assets and liabilities.
Market risk: Equity prices and other asset values may fall despite changes in monetary policy.
Investors should assess these risks before committing capital and seek qualified financial advice when necessary. No investment strategy can guarantee profits or eliminate the possibility of losses.
Navigating changing economic conditions requires more than following headlines. It involves understanding financial instruments, assessing market information, matching investments to financial objectives, and monitoring risks over time.
Professional investment management can help investors evaluate available opportunities, understand the trade-offs between liquidity and potential returns, and make decisions within a structured investment strategy.
At Tro-Vest Capital Partners, we recognise the importance of informed financial decisions and a clear understanding of the economic environment. Through our financial services, we aim to help individuals and businesses better understand investment considerations and explore solutions aligned with their financial needs.
Before choosing an investment product, investors should understand its objectives, costs, liquidity provisions, regulatory status, and associated risks. Past performance and published yields should not be treated as guarantees of future results.
The CBN’s September 2026 MPC decision to reset the Monetary Policy Rate from 26.5% to 23% represents an important adjustment to Nigeria’s monetary policy framework.
However, the CBN has clarified that the move is primarily an operational recalibration rather than a straightforward shift towards monetary easing. Its impact on borrowing costs, investment yields, asset prices, and business activity will depend on how financial markets respond and how broader economic conditions develop.
For investors, the key lesson is to look beyond the headline rate. Reviewing fixed-income holdings, comparing market yields, assessing company fundamentals, managing currency exposure, and maintaining an appropriate investment strategy can help investors respond more thoughtfully to changing conditions.
In a dynamic economy, informed decisions are an important part of building financial resilience and pursuing long-term wealth.
Ready to make more informed investment decisions? Explore the financial services offered by Tro-Vest Capital Partners and learn more about the considerations that can help you plan your financial future.
Visit the Tro-Vest Capital Partners website to learn more about our services.
Disclaimer: This article is for educational and informational purposes only and does not constitute investment, legal, tax, or financial advice. Investment decisions should be based on individual circumstances, appropriate due diligence, and an understanding of the risks involved. Investment values and returns can rise or fall, and investors may lose some or all of their capital.